

For the roughly 75 people whose jobs have been preserved at Runcorn, the sale of Vynova’s chemical manufacturing assets is welcome news. For businesses that depend on Britain’s chemical producers, it carries a more awkward message: even an operation of national importance can end up in administration.
Related Reading:
Chemical Engineering Industry Analysis
Jackdaw gets the green light despite North Sea struggles
Chemical Manufacturing Industry Analysis
TheBusinessDesk reports that Inovyn ChlorVinyls has acquired the company’s ethylene dichloride plant, related assets and its 50% shareholding in Runcorn MCP for an undisclosed sum. The transaction gives the operation a future under new ownership and reassures the industrial network around it.
The wider picture gives that warning substance. Each of Plimsoll’s two analyses places more than one in five companies in the Danger category, even as other businesses achieve strong growth. For directors, the rescue raises a practical question: which suppliers, customers and competitors have the financial strength to withstand further pressure?
Why the Runcorn rescue matters beyond Cheshire
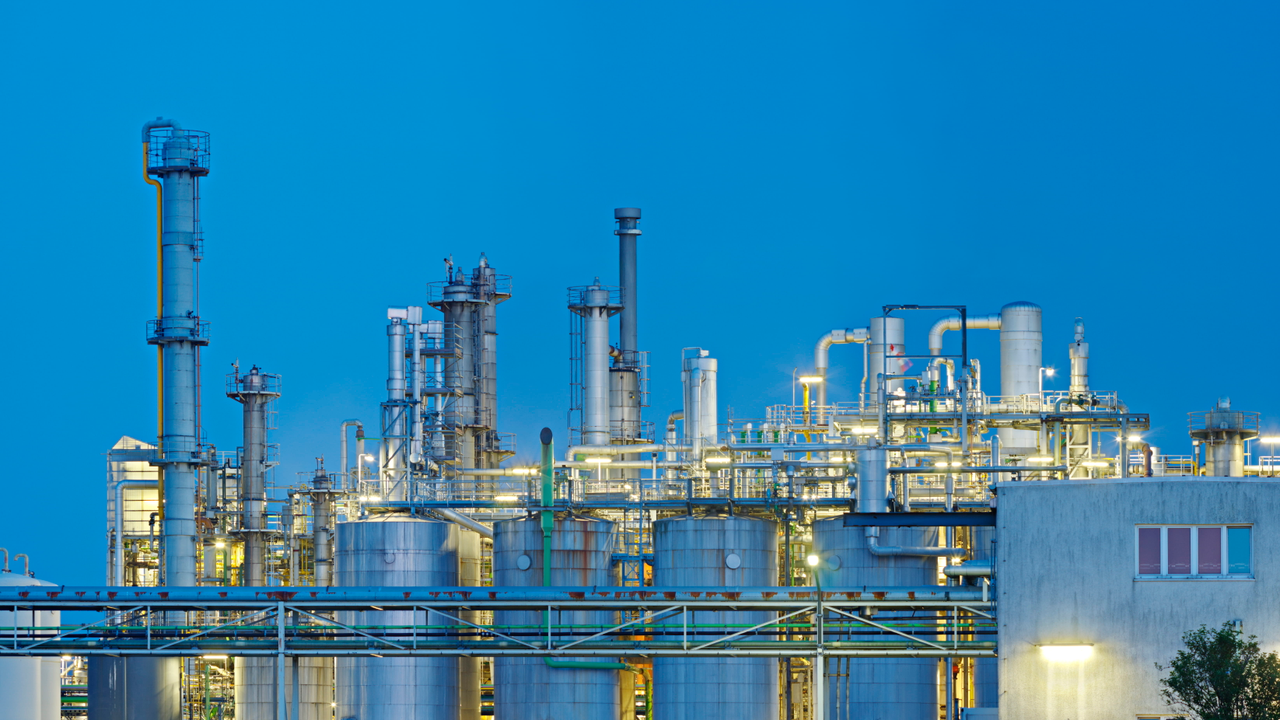
Ethylene dichloride, or EDC, is a building block used in producing PVC. According to INEOS’s announcement, the acquired operation is the UK’s only EDC asset, and the transaction brings the EDC and chlor-alkali production chain at Runcorn together under INEOS Inovyn.
The wider Runcorn site also has a vital role in water treatment. INEOS says it supplies around 98% of the chlorine used in drinking-water treatment. Its significance extends into the most ordinary and essential routines of daily life.
Such interdependence changes the significance of a rescue. A factory’s importance can extend through customers and neighbouring operations whose own production depends on its continued existence. Keeping an industrial capability in place can therefore protect value well beyond the assets being sold.
Yet strategic importance cannot pay an energy bill. Alongside its announcement, INEOS called for lower energy, carbon and compliance costs, as well as trade protection. The buyer’s message is clear: preserving a vital asset also requires an environment in which it can operate competitively.
What the two Plimsoll analyses reveal about financial pressure
Plimsoll’s Chemical Manufacturing Industry Analysis covers 527 companies, while its separate Petrochemicals Industry Analysis examines 137. Both show declining average sales, but their modest headline contractions conceal a more uneven commercial landscape.
|
Published measure |
Chemical Manufacturing |
Petrochemicals |
|
Companies analysed |
527 |
137 |
|
Average sales growth |
−0.9% |
−0.3% |
|
Profitability benchmark |
4.1% |
5.0% |
|
Companies rated in danger |
121 |
28 |
|
Share rated in danger |
23.0% |
20.4% |
|
Losses for a second year |
93 |
18 |
|
Companies with falling sales |
254 |
70 |
|
Companies growing by more than 10% |
43 |
18 |
|
Highly attractive acquisition prospects |
137 |
40 |
Source: the two Plimsoll portal pages, accessed 3 November 2026. Danger percentages are calculated from each report’s company total. The report populations may overlap and have not been combined.
Chemical manufacturing has the weaker sales and profitability benchmarks, alongside a higher proportion of companies rated in danger. Petrochemicals looks somewhat stronger on those measures, yet more than half its covered companies are selling less than a year earlier. Neither market can be understood through its average alone.
Recurring losses sharpen the concern: 93 chemical manufacturers and 18 petrochemicals businesses have recorded losses for a second consecutive year. A Danger rating is a financial assessment, not an insolvency prediction, but sustained losses give trading partners good reason to examine resilience.
Both markets also show meaningful growth. Companies expanding by more than 10% show how much individual performance can deviate from prevailing conditions. The question is whether that growth produces sustainable returns or leaves a business with more activity but less financial strength.
How supplier weakness becomes a customer problem
For a customer, a supplier’s financial position becomes operationally significant when there is little room to replace it. The relevant questions begin with dependency: how much production relies on that relationship, what alternatives are available, and how long would it take to qualify them?
Financial analysis helps determine where that review deserves attention. A deteriorating margin or a weakening balance sheet should prompt a closer conversation about capacity, investment and continuity. It does not, by itself, prove that a delivery will fail. The purpose is to make contingency planning proportionate to the evidence.
Suppliers face the exposure from the opposite direction. A substantial customer may support a healthy order book while leaving the business dangerously dependent on a single stream of payments. Reviewing customer concentration alongside financial performance can reveal where growth is creating vulnerability.
What buyers can learn from an industrial rescue
Plimsoll identifies 137 highly attractive acquisition prospects in chemical manufacturing and 40 in petrochemicals. Those classifications provide a starting point for investigation; they do not establish that the businesses are distressed or available to buy. The opportunity may lie in acquiring a sound operator with capabilities a buyer can develop.
Runcorn also shows why acquiring industrial assets requires a broader assessment than the purchase price. Penningtons Manches Cooper, which advised the administrators, describes a transaction conducted through a conventional M&A framework despite the administration, with conditions to satisfy between agreement and completion.
The firm also reports that two pension scheme sections were taken out of Pension Protection Fund assessment and transferred to INEOS Inovyn sponsorship. Preserving the operation therefore involved arrangements reaching well beyond its machinery and property.
For a prospective buyer elsewhere in the sector, the lesson is to examine what makes the business viable in their hands. That includes the fit with existing operations, future investment needs and the resources required to sustain production. A low price offers little comfort if the buyer has underestimated the work still to be done.
Plimsoll’s Industry Analysis supports the earlier stages of that assessment by comparing company performance, financial health and acquisition attractiveness. It can help directors identify businesses deserving closer investigation and assess their position against competitors. Detailed operational, legal and financial due diligence must then establish whether a proposed acquisition makes sense.
The immediate outcome at Runcorn is a welcome one: skilled jobs and industrial capability have been preserved. The wider lesson is to take financial resilience seriously before a rescue is needed. For companies buying from, supplying or competing with chemical manufacturers, that starts with understanding the businesses behind the names on the order book.